
Market News

Forex Market News .. collected from serval sources, all in one place for you to review.
[most entries here, will be auto-removed after 90 days]

Monday 28th September 2026: Stock Futures Fall as Oil Rises and Treasury Yields Hit Multiyear Highs

Global Markets:

●         Asian Stock Markets : Nikkei up 0.02%, Shanghai Composite down 1.74% Hang Seng up 0.54% ASX up 0.30%

●        Commodities : Gold at $4,231.90 (-2.06%) Silver at $62.500 (-3.56%), Brent Oil at 99.01 (1.60%), WTI Oil at 94.00 (1.71%)

●        Rates : US 10-year yield at 5.209, UK 10-year yield at 5.3593, Germany 10-year yield at 3.6210

News & Data:

●        (USD)    Revised UoM Consumer Sentiment

        48.1 to 47.4  expected

Markets Update:

U.S. stock futures fell early Monday after equities posted weekly gains, as rising oil prices and surging Treasury yields weighed on sentiment.

Dow Jones Industrial Average futures declined 180 points, or 0.4%, while S&P 500 futures slipped 0.4%.…
Read source

Monday 28th September 2026: Technical Outlook and Review

  DXY (U.S. Dollar Index):

Potential Direction: Bullish

Overall momentum of the chart: Bearish

The price could see a short-term pullback before rebounding and continuing its bullish move toward the 1st resistance.

Pivot: 100.11
Supporting reasons: Identified as a pullback support, where renewed buying pressure could emerge to support further upside.

1st support: 98.56

Supporting reasons: Identified as a swing-low support, marking a previous area where buying pressure emerged, and price could potentially stabilize again. 

1st resistance: 101.59
Supporting reasons: Identified as a swing-high resistance, marking a previous area of selling pressure that could potentially cap further upside. 

EUR/USD:

Potential…

Read source

Market outlook for the week of 28th September – 2nd October

Monday starts slow with nothing significant in terms of scheduled economic events for the FX market. On Tuesday the highlights will be the RBA monetary policy announcement, Canada's GDP m/m, and the U.S. CB consumer confidence and JOLTS job openings prints.

On Wednesday, we'll get inflation data for Australia following the RBA meeting and for the U.S., the ADP non-farm employment change, core PCE price index m/m and final GDP q/q. Thursday will bring the U.S. the unemployment claims and ISM manufacturing PMI.

Finally, on Friday data releases will include the Tokyo core CPI y/y, the eurozone inflation figures, and the U.S. average hourly earnings m/m, non-farm employment change and unemployment rate. 

Several FOMC members are expected to…

Read source

US jobs report could decide how much higher Treasury yields can go

It's only Monday but it feels like markets already have plenty to digest this week.

Geopolitical tensions remain up in the air. Higher oil prices. Surging bond yields. Stocks and gold under threat again. It's all to play for with month-end and quarter-end volatility also set to kick into gear.

But in terms of macro catalysts, the big one is arguably the US jobs report that will only come on Friday.

The main worry for markets right now isn't that employment conditions suddenly look weak. It's almost the opposite.

US economic activity has remained surprisingly resilient despite higher rates, and that resilience is becoming more and more difficult for the bond market to ignore. The September flash composite PMI jumped to 58.4, its strongest…

Read source

The Week Ahead – Week Commencing 28 September 2026

Markets endured another lively week last week, with global bond yields surging and volatility remaining elevated as geopolitical concerns continued to dominate sentiment.

The week ahead has the potential to be even more volatile. Geopolitical headline risk will remain firmly in focus, while a packed macroeconomic calendar should keep traders on their toes throughout the week.

The US calendar is particularly busy, with several employment updates due ahead of Friday’s key Non-Farm Payrolls report. The Fed’s preferred inflation measure, the Core PCE Price Index, will also be released and could generate significant moves across currencies, equities and bond markets.

There are several important updates scheduled in other major…

Read source

General Market Analysis – 28/09/26

US Stocks Rally into the Weekend – Dow up 0.9%

US equity markets finished the trading week on a positive note on Friday, with all three major indices advancing as technology stocks once again helped support sentiment. The Dow Jones gained 0.93% to close at 51,828, while the S&P 500 rose 0.51% to 7,743. The Nasdaq also moved higher, adding 0.48% to finish the session at 27,068.

US Treasury yields retreated from recent highs as some buying returned to the bond market. The policy-sensitive 2-year yield fell 7.3 basis points to 4.852%, while the benchmark 10-year yield declined 3.7 basis points to 5.160%. The pullback in yields also weighed on the US dollar, with the Dollar Index dropping 0.25% to close at 101.04.

The yen was a key…

Read source

FX option expiries for 28 September 10am New York cut

There are just a couple of key expiry levels to watch out for today, as highlighted in bold below.

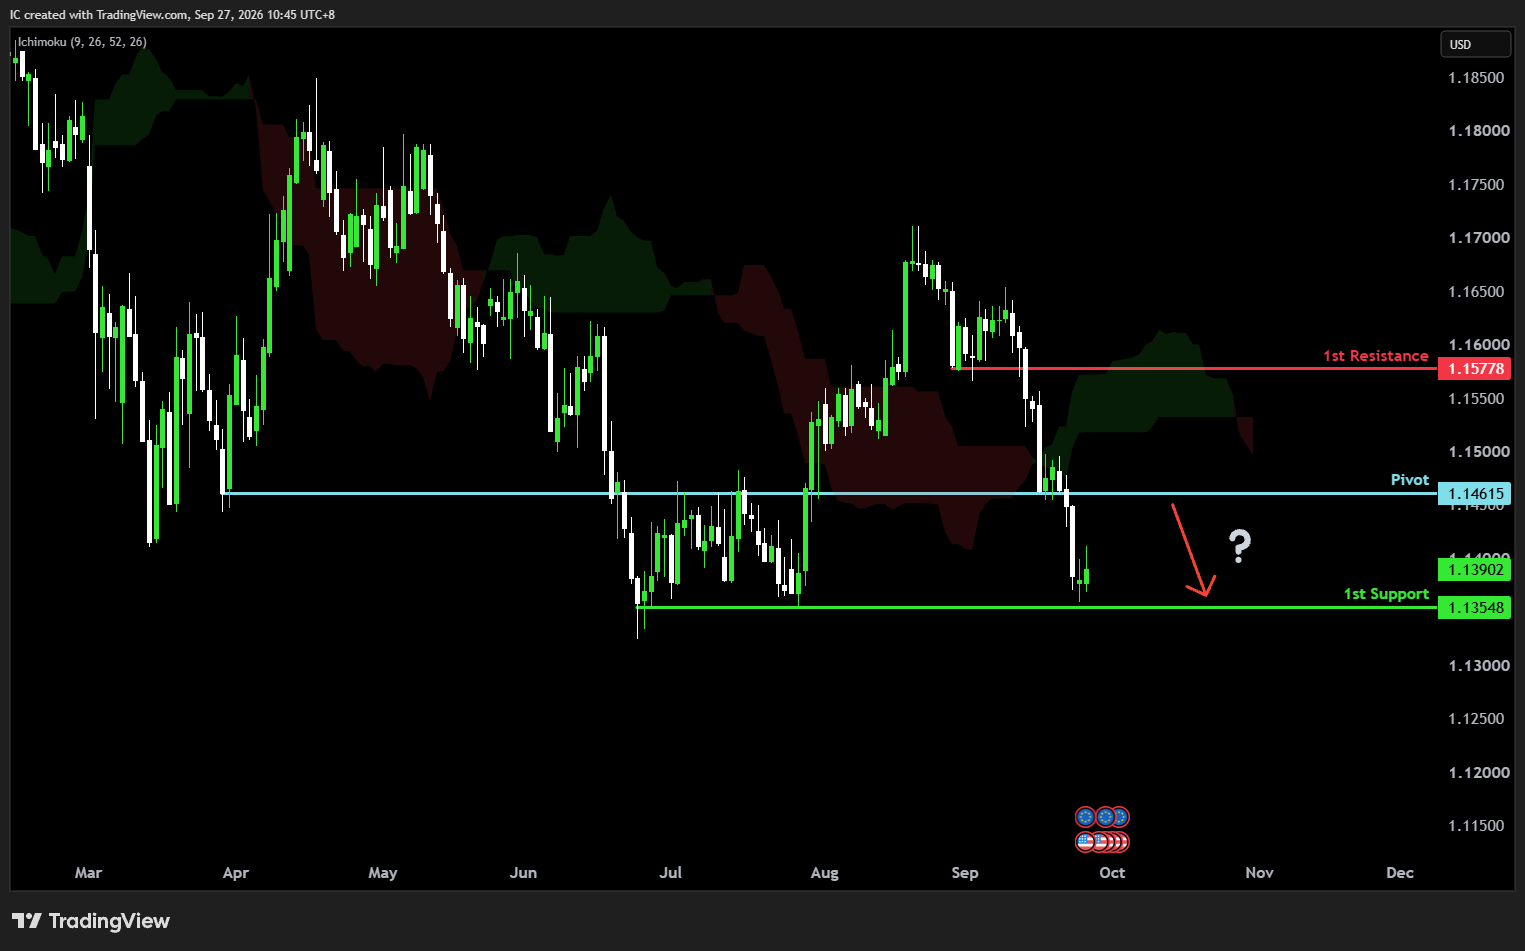
They are for EUR/USD at the 1.1350 and 1.1400 levels, sandwiching the current spot price within 15-35 pips of the respective strikes. The €4.5 billion expiry at 1.1400 is the standout. It is both exceptionally large and almost sitting on top of current price, while 1.1400 is also an obvious psychological level.

In adding to that, the 100-hour moving average sits at 1.1404 currently. So, that will add a key near-term technical resistance layer in keeping price action capped closer to the 1.1400 region in the session ahead.

As such, the expiry at the figure level could give EUR/USD a gravitational pull towards 1.1400 heading into the cut -…

Read source

Stock earnings pick of the week: Can Micron earnings keep the AI memory boom running?

We'll finally have a notable tech name to watch on the earnings calendar this week.

Micron will be reporting its fiscal fourth-quarter earnings on Wednesday, and expectations are hardly modest.

The company itself is guiding for revenue of around $50 billion, an adjusted gross margin of roughly 86% and adjusted EPS of close to $31.00. Meanwhile, market expectations are also thereabouts with $50.4 billion in revenue and $31.14 in EPS estimated ahead of the earnings call.

The numbers here follows from an already exceptional third quarter, when Micron delivered $41.46 billion in revenue and $25.11 in adjusted EPS.

But with most tech earnings, I think the headline numbers would almost certainly take a back seat. Perhaps the more interesting…

Read source

Gold price breaks below $4,200 as surging Treasury yields deepen the technical damage

It's a brand new week but same old struggles for gold. The precious metal is kicking things off with another leg lower today, falling below $4,200 to its lowest in almost eight weeks. That as the pressure from the bond market continues to build.

This time around, there is a more meaningful technical break to go alongside it.

For the better part of the past two weeks, we've seen price action consolidate between $4,240 to $4,400. Buyers have stepped in to defend the $4,240 floor on just a few ocassions, with that lining up with the 61.8 Fib retracement level at around $4,241 on the chart. But now, that floor looks to be giving way and is leaving gold trading at its lowest level since early August.

That continues to reinforce the narrative that…

Read source

Nikkei gives up early gains as Nasdaq futures slip before Micron earnings

The turn in Nasdaq futures shows how closely Japanese equities are tied to US chip sentiment, so Micron's results on Wednesday are the near-term catalyst. One analyst quoted by Reuters expects the US semiconductor index to stay inside a wide trading range for the next three to four months, and the Nikkei is likely to mirror it. That points to choppy, two-way trade rather than a clean breakout for now. The same analyst flagged a longer-run risk for bank shares, which could lose support once the Bank of Japan's policy rate approaches its terminal level.

---

Japan earlier:

---

The Nikkei's morning…

Read source

Treasury’s $202 billion settlement is routine, not a Bitcoin trigger

Repo funding is the part of this story with real substance. Quarter end is a seasonal pinch point for overnight borrowing costs, and the added coupon supply gives dealers more to fund at once, which is why the Federal Home Loan Bank of New York flagged the risk even while calling current conditions calm. A brief spike in SOFR around settlement would be unremarkable and likely to fade. Persistent pressure would matter more, and traders will be watching whether it shows up in Bitcoin funding rates or futures premiums rather than assuming a link exists. Bitcoin's current position near $84,000 already reflects a tougher macro backdrop, with the 10 year Treasury yield at its highest since 2007 and rate hike odds elevated, so any move after…

Read source