
Market News

Forex Market News .. collected from serval sources, all in one place for you to review.
[most entries here, will be auto-removed after 90 days]

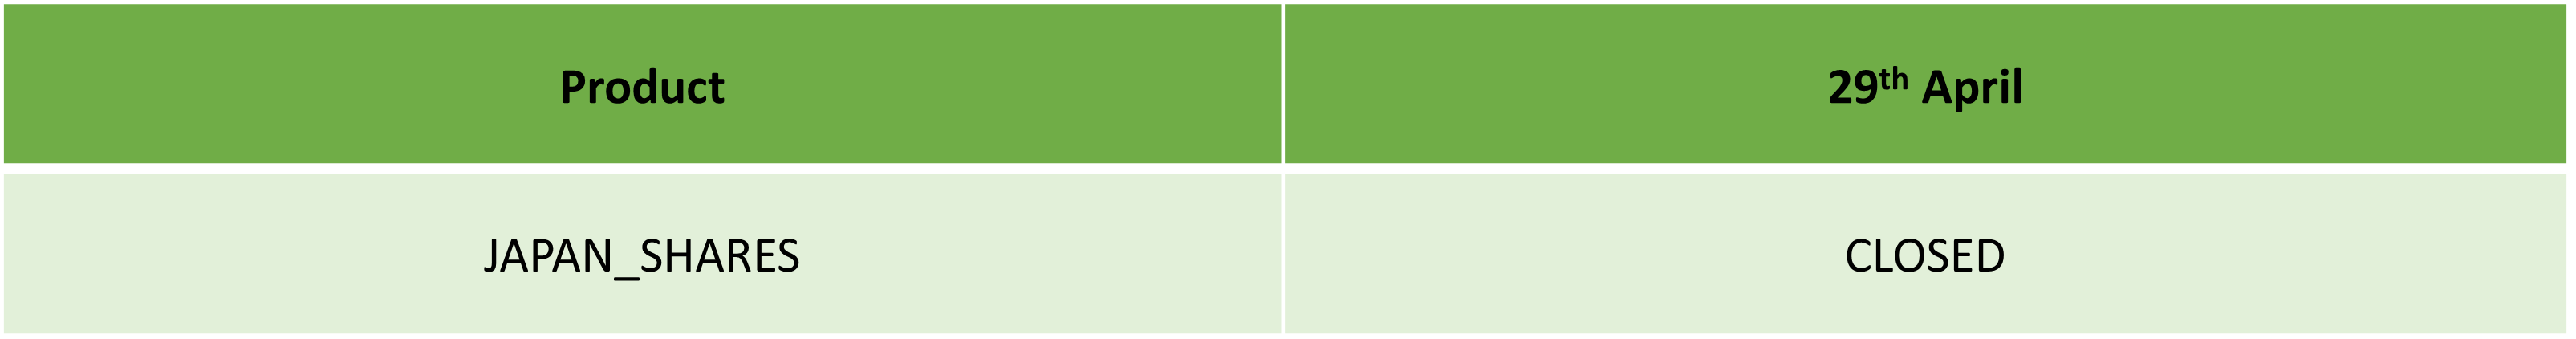
Japanese Showa Day Holiday Trading Schedule 2026

Dear Client,

Please find our updated Trading schedule and general information related to the Japanese Showa Day on Wednesday, 29 April, 2026. 

Liquidity over the holidays is expected to be particularly thin so please take the necessary precaution to ensure that you are not affected by increased volatility, spreads and intermittent pricing.

All times mentioned below are Platform time (GMT +3).
Kind regards,

IC.

The post Japanese Showa Day Holiday Trading Schedule 2026 first appeared on IC Your Trading Edge | Official Blog.
Read source

US consumers, importers are the ones suffering the most from tariffs – ECB study

The study notes that the costs of tariffs enacted by the Trump administration are "falling mostly on domestic importers and consumers". In putting a number to that, the study reveals that US consumers are bearing around a third of the tariff burden currently. And if the tariffs are going to stay for longer, that cost will increase even more.

For now, it is noted that US exporters are only absorbing a small fraction of the higher tariff-related costs. It is being estimated that a 10% increase in tariffs implies only a 9.5% increase in prices.

Overall, it is a tough situation for US consumers. The current estimate shows that they are already being burdened by about a third of the cost. But if US firms exhaust their ability to absorb the…

Read source

Monday 30th March 2026: Asia-Pacific Markets Slide as Middle East Conflict Deepens, Oil Prices Rise

Global Markets:
  •  Asian Stock Markets : Nikkei down 3.34%, Shanghai Composite up 0.23% Hang Seng down 0.94% ASX down 0.83%
  • Commodities : Gold at $4,533.51 (0.20%) Silver at $70.145 (0.50%), Brent Oil at $107.71 (2.26%), WTI Oil at $101.57 (1.92%)
  • Rates : US 10-year yield at 4.391, UK 10-year yield at 4.9740, Germany 10-year yield at 3.0985
News & Data:
  • (GBP) Retail Sales m/m  -0.4%  to -0.6%  expected
Markets Update:  

Asia-Pacific markets dropped sharply on Monday as the Middle East conflict entered its fifth week, intensifying despite ongoing diplomatic efforts. South Korea’s benchmark Kospi plunged more than 5%, while the small-cap Kosdaq declined 3.97%.

Japan’s Nikkei 225 slipped 3.97% and the Topix lost…

Read source

IC Markets Global – Europe Fundamental Forecast | 30 March 2026

IC Markets Global – Europe Fundamental Forecast | 30 March 2026

What happened in the Asia session?

Asia’s session today opened with a risk‑off tilt, driven by an extended pause on US military strikes against Iranian energy infrastructure, elevated oil prices, and negative handovers from Wall Street and European indices. Japanese, Korean, and Australian equities opened softer, with tech and semis among the weakest, while India‑related indices were also expected to start weak beneath higher India‑VIX.

What does it mean for the Europe & US sessions?

Today’s European and U.S. trading session is being shaped by cautious risk appetite, elevated U.S. Treasury yields, and fresh worries about private‑credit and geopolitical fallout, while traders…

Read source

Bavaria March CPI +2.8% vs +1.9% y/y prior

The other state releases around the same time:

  • Brandenburg CPI +% vs +2.0% y/y prior
  • Hesse CPI +% vs +2.2% y/y prior
  • Saxony CPI +% vs +2.3% y/y prior
  • North Rhine Westphalia +% vs +1.8% y/y prior
  • Baden Wuerttemberg CPI +% vs +1.8% y/y prior

More to come..

This article was written by Justin Low at investinglive.com.
Read source

IC Markets Global – Asia Fundamental Forecast | 30 March 2026

IC Markets Global – Asia Fundamental Forecast | 30 March 2026

What happened in the U.S. session?

The main driver was not a fresh macro headline but the ongoing Middle‑East conflict and its inflationary, energy‑cost overhang, which kept oil elevated and U.S. equities in a cautious, quarter‑end correction while defensive and commodity‑linked assets were relatively better‑supported; with no major U.S. data actually released on the session, the primary market reaction was in positioning for the coming week’s key U.S. labor‑market and consumer‑confidence releases, leaving Treasuries and the dollar in a range‑bound but biased‑higher‑yield stance ahead of the next data‑driven event risk.

What does it mean for the Asia Session?

Monday’s Asia…

Read source

Monday 30th March 2026: Technical Outlook and Review

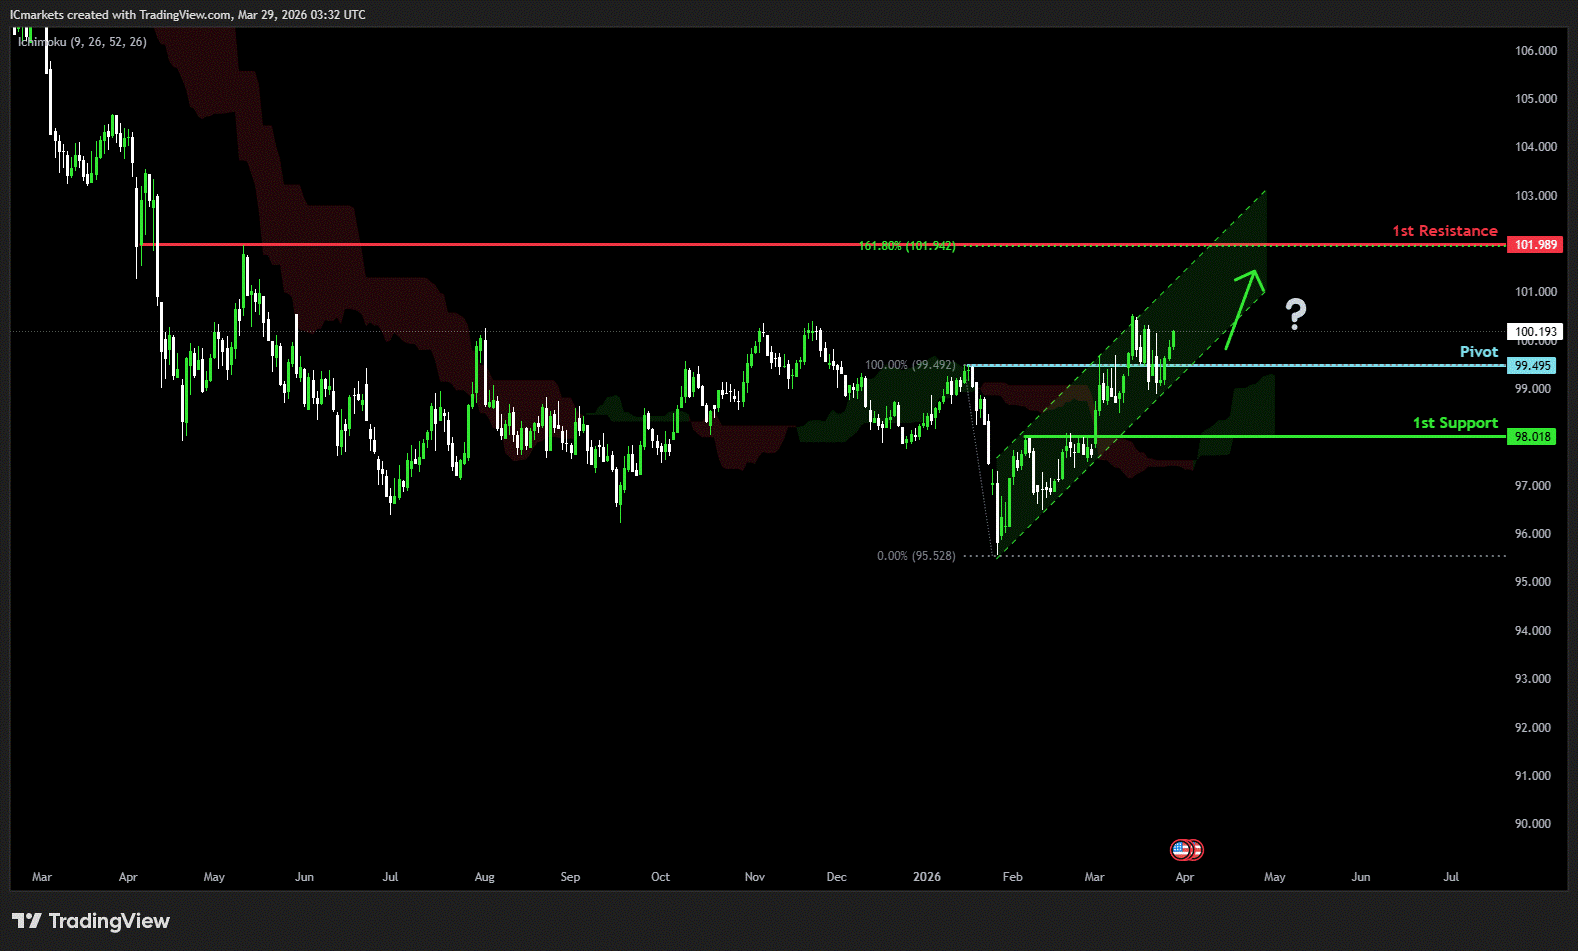
  DXY (U.S. Dollar Index):

Potential Direction: Bullish

Overall momentum of the chart: Bearish

The price could make a short-term pullback toward the pivot before rising again toward the 1st resistance.

Pivot: 99.49

Supporting reasons: Identified as a pullback support, where renewed buying pressure could emerge to push the price higher.

1st support: 98.01

Supporting reasons: Identified as a pullback support, indicating a potential area where the price could again stabilize.

1st resistance: 101.98
Supporting reasons: Identified as an overlap resistance that aligns with the 161.8% Fibonacci retracement, indicating a potential area that could halt any further upward movement

EUR/USD:

Potential Direction:…

Read source

The Week Ahead – Week Commencing 30 March 2026

Markets remained highly volatile in the last week as the conflict in the Middle East raged on, and investors started to price in prolonged disruption to oil flow. Updates over the weekend that the Houthis have started to hit Israel with missiles and US marines have arrived in the region may lead to some gapping again on the Monday open.

Once again, geopolitical updates are expected to dominate the market this week; however, there are some major data releases due out of the US, including the big employment numbers, as well as anticipated liquidity thinning as markets move into the Easter weekend, and so traders are expecting another lively week ahead.

Here is our usual day-by-day breakdown of the major risk events this…

Read source

General Market Analysis – 30/03/26

Markets Under Pressure on Conflict Concerns into the Weekend – Nasdaq down 2%

Global financial markets closed the week under pressure, with risk sentiment continuing to deteriorate as developments in the Middle East showed little sign of easing. Ongoing uncertainty around the conflict kept investors cautious, driving a broad-based sell-off across US equities into Friday’s close. The Dow Jones fell 1.73% to 45,166, while the S&P 500 declined 1.67% to 6,368, while the tech-heavy Nasdaq led losses, dropping 2.15% to finish at 20,948. In currency markets, the US dollar remained well supported, with the DXY rising 0.29% to 100.19, closing near annual highs as safe-haven demand continued to underpin the greenback. US Treasury markets were…

Read source

Heads up: Germany states’ CPI readings due later today

This will be quite the anticipated report to watch in the session ahead. Prior to the US-Iran conflict, German inflation was already the key sticking point for the ECB in preventing the central bank from pursuing further rate cuts. Price pressures in Europe's largest economy have been stubborn and showed little signs of waning upon the turn of the year.

So when you factor in the Middle East developments in the past month, everything is turning up bad again. German manufacturing had been on the recovery path upon the turn of the year. And that has helped to alleviate some pressures on the economy for a while now.

But with prices set to hit harder there amid surging input cost inflation, that will be a key challenge for the manufacturing…

Read source

Bond managers warn markets underestimate growth risks from Iran war

Bond giants see growth shock ahead as markets fixate on inflation

Summary:

  • Major bond managers warn markets are underestimating growth risks from the U.S.–Iran war, according to Bloomberg.
  • Oil above $110 has driven a Treasury selloff, with yields surging on inflation fears.
  • Investors expect the Fed to stay tight or even hike, pushing bonds toward their worst month since Oct 2024.
  • However, firms like PIMCO, JPMorgan Chase and BlackRock see a growth slowdown that could reverse yields lower.
  • Key debate: inflation shock now vs recession risk next.

Some of Wall Street’s largest bond investors are increasingly warning that financial markets are focusing too heavily on inflation risks from the U.S.–Iran war, while underestimating the growing…

Read source