
Market News

Forex Market News .. collected from serval sources, all in one place for you to review.
[most entries here, will be auto-removed after 90 days]

White House submits nomination of Kevin Warsh for Fed Chair to Senate

The White House has submitted the nomination of Kevin Warsh for the Fed chair to the Senate

Recall, it was announced on January 30, 2026 that Kevin Warsh would be nominated as the next Federal Reserve Chair.

  • January 30, 2026: President Donald Trump announced his intention to nominate Warsh to succeed Jerome Powell when Powell’s term as chair ends in May 2026.

  • The nomination still requires U.S. Senate confirmation before Warsh can officially assume the role.

  • Warsh previously served as a Federal Reserve Governor from 2006 to 2011.

It appears the urgency to fast-track Kevin Warsh’s vetting and approval—potentially to increase pressure on the Fed to cut rates—has faded as inflation remains elevated and growth and employment continue to show…
Read source

EIA Crude oil inventories 3.475M vs 2.305M estimate

  • Crude oil 3.475M vs 2.305M estimate. Last 15.989M
  • Distillates 0.429M vs -2.596M estimate. Last 0.252M
  • Gasoline -1.704M vs 0.784M last week.
  • Cushing 1.564M vs 0.881M last week.

The private data released late yesterday showed:

  • Crude +5.6M
  • Distillates +0.5M.
  • Gasoline -3.3 million
  • Cushing +1.5 million

Crude oil is trading lower on the day after failing to sustain yesterday’s rally. The price extended to just below $78 yesterday, but today’s rebound stalled at $77.23 before sellers stepped back in. The session low has reached $73.28, keeping the focus on nearby technical support levels.

On the downside, the 38.2% retracement of the move up from the February 26 low at $63.60 comes in at $72.49. Yesterday the price briefly dipped below that level but…

Read source

ISM non-manufacturing PMI for February 56.1 versus 53.5 estimate

  • Prior month 53.8
  • ISM non- manufacturing PMI for February 56.1 versus 53.5 estimate.
  • Nonmanufacturing business activity 59.9 vs 57.4 last month
  • employment index 51.8 vs 50.3 last month.
  • New orders 58.6 vs 53.1 last month.
  • Prices paid 63.0 vs 66.6 last month. The index has exceeded 60 percent for 15 straight months, but February’s reading is its lowest since March 2025 (61.4 percent).
  • Inventories 56.4 versus 45.1 last month. The Inventory Sentiment Index expanded for the 34th consecutive month, registering 55.3 percent, up 1 percentage point from January’s figure of 54.3 percent.
  • Supplier deliveries 53.9 versus 54.2 last month
  • Backlog of orders 55.9 versus 44.0 last month. The Backlog of Orders Index was in expansion territory for the first time…
Read source

Canada Labor Productivity rate for Q4 -0.1% vs -0.1% estimate

  • Prior quarter 0.9% revised to 1.1%
  • Labor productivity rate for Q4 -0.1% vs -0.1% estimate

Details of the report:

  • Canadian business labour productivity fell -0.1% in Q4, as real GDP declined -0.2% while hours worked fell -0.1%.

  • This follows a +1.1% productivity gain in Q3, when output rose while hours worked declined.

  • The Q4 drop marks the second productivity decline in the last nine quarters.

Sector breakdown

  • Goods-producing sector productivity fell -0.9% in Q4, after rising +1.8% in Q3.

  • Services sector productivity rose +0.4%, following +0.6% growth in the prior quarter.

  • Manufacturing and construction were the main drivers of the productivity decline.

  • Information and cultural industries led productivity gains within services.

Hours worked

  • Total…

Read source

US February ADP employment +63K vs +50K expected

  • Prior was +22K (revised to +11K)
  • Goods +16K versus +1K last month
  • Service +47K versus +21K last month
  • Small business +60K vs 0K prior
  • Medium businesses -7K vs +41K last month
  • Large businesses +10K vs -18K last month
  • Wages for job stayers 4.5% vs 4.5% last month
  • Wages for job changers 6.3% vs 6.4% last month

This shouldn't be surprising given that the weekly ADP data has been pointing to a good report. The labour market has been improving steadily since the start of the year. On Friday, we get the more important US NFP report, which is likely to be a good one based on all of the jobs data we got up until now.

For background, the ADP National Employment Report is an independent monthly measure of private-sector employment in the United States,…

Read source

IC Markets Global – Europe Fundamental Forecast | 04 March 2026

IC Markets Global – Europe Fundamental Forecast | 04 March 2026

What happened in the Asia session?

Today’s Asia session saw markets grappling with escalating US-Iran tensions, which overshadowed key macroeconomic data releases like China’s ongoing policy signals ahead of the ‘Two Sessions’ meetings (March 4-11) and Australia’s Q4 current account deficit data showing export weakness. Escalating geopolitical risks drove oil prices toward $80/barrel amid supply disruption fears, boosting energy stocks while hammering airline, tourism, and broader equities.

What does it mean for the Europe & US sessions?

Escalating geopolitical tensions from the U.S.-Iran conflict, which have driven a sharp Dow drop of 1,200 points, surging oil prices,…

Read source

Wednesday 4th March 2026: Technical Outlook and Review

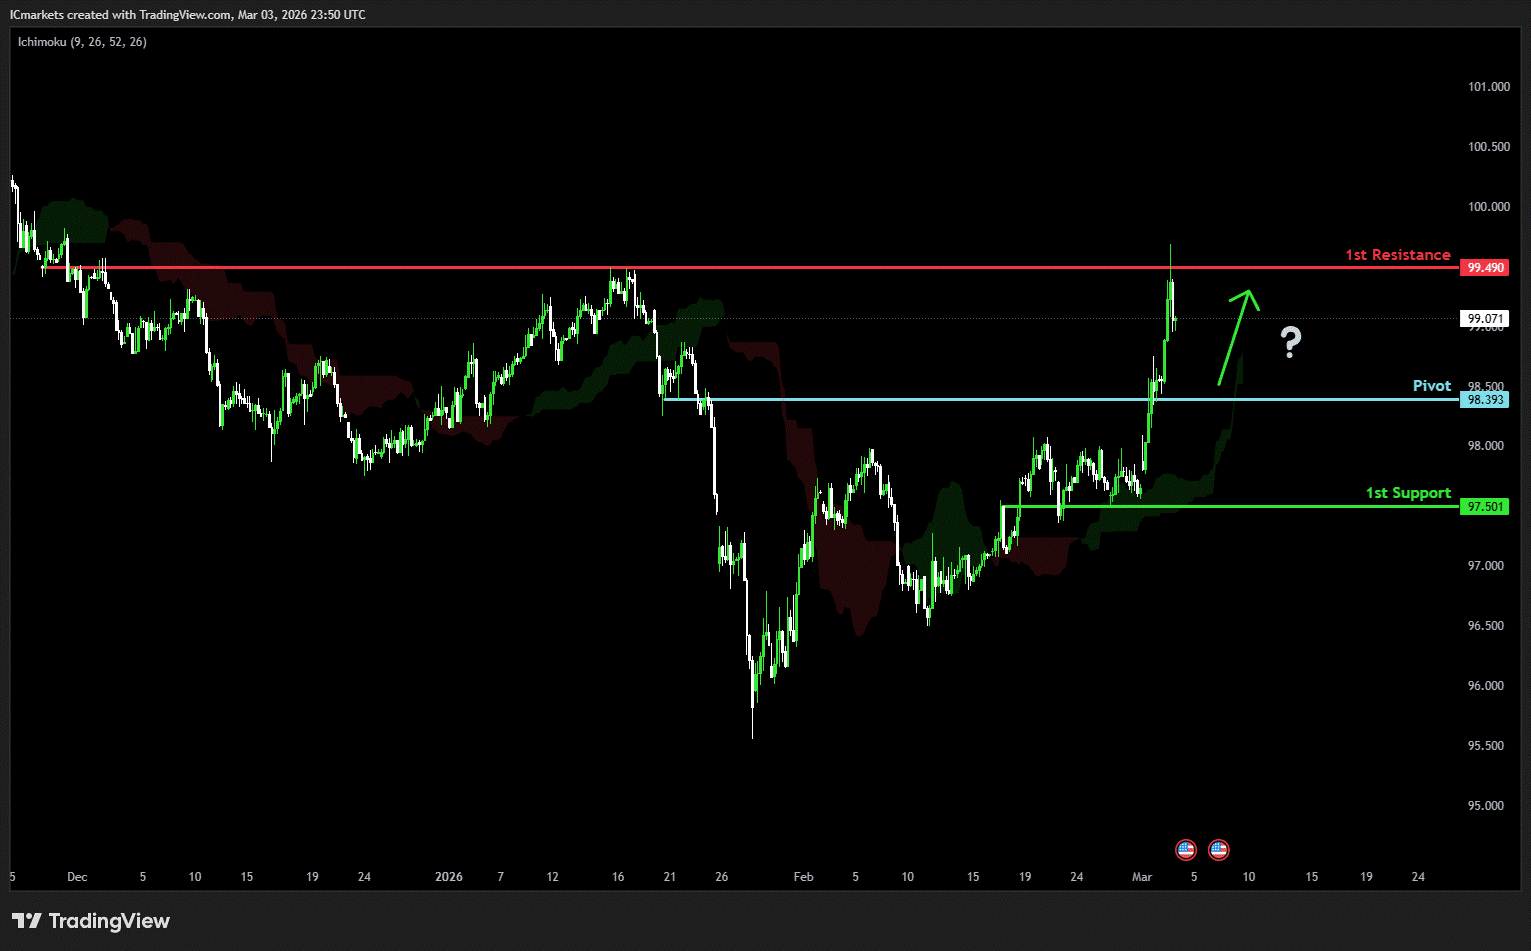
  DXY (U.S. Dollar Index):

Potential Direction: Bullish

Overall momentum of the chart: Bearish

The price could see a short-term pullback toward the pivot before rising again toward the 1st resistance.

Pivot: 98.39

Supporting reasons: Identified as a pullback support, where renewed buying pressure could emerge to push the price higher.

1st support: 97.50

Supporting reasons: Identified as an overlap support, indicating a potential area where the price could again stabilize.

1st resistance: 99.49
Supporting reasons: Identified as an overlap resistance, indicating a potential area that could halt any further upward movement

EUR/USD:

Potential Direction: Bearish

Overall momentum of the chart:…

Read source

Wednesday 4th March 2026: Asian Markets Slide as Middle East Conflict Drives Oil Prices Higher and Fuels Inflation Fears

Global Markets:
  •  Asian Stock Markets : Nikkei down 3.91%, Shanghai Composite down 1.43%, Hang Seng down 2.85% ASX down 2.02%
  • Commodities : Gold at $5,179.66 (1.07%) Silver at $85.093 (1.95%), Brent Oil at $82.60 (1.46%), WTI Oil at $75.36 (1.07%)
  • Rates : US 10-year yield at 4.065, UK 10-year yield at 4.4640, Germany 10-year yield at 2.7752
News & Data:
  • (EUR) Core CPI Flash Estimate y/y  2.4%  to 2.2%  expected
Markets Update:  

Asian stock markets declined sharply on Wednesday following weak global cues, as investors grew increasingly concerned about the inflationary impact of the ongoing Middle East conflict, which has now entered its fifth day. U.S. President Donald Trump suggested the war could last four to…

Read source

General Market Analysis – 04/03/26

Stocks Hit as Middle East Conflict Escalates – S&P down 1%

Global financial markets experienced a broad-based selloff overnight as escalating tensions in the Middle East dampened hopes of a swift resolution and reignited inflation concerns. Risk sentiment deteriorated throughout the session, with equity markets finishing firmly in negative territory despite a late attempt at stabilisation. During the US session, Donald Trump stated that the United States would escort commercial shipping through the Strait of Hormuz, offering some reassurance to markets. The Dow Jones declined 0.83% to finish at 48,501, while the S&P 500 fell 0.94% to 6,816. The technology-heavy Nasdaq Composite led the retreat, shedding 1.02% to close at 22,516. In…

Read source