
Market News

Forex Market News .. collected from serval sources, all in one place for you to review.
[most entries here, will be auto-removed after 90 days]

Canada January GDP +0.1% vs 0.0% expected

  • Prior was +0.2%
  • Q4 GDP was -0.6%
  • Goods-producing industries expanded by 0.2% for the second month in a row
  • Services-producing industries were essentially unchanged in January
  • 9 of the 20 industrial sectors recorded growth in January.

Canada's economy closed out 2025 on shaky ground, and today's January monthly GDP release arrives at a moment of heightened uncertainty. Real GDP grew just 1.7% for the full year of 2025, the slowest annual pace since the pandemic-driven contraction of 2020, with lower exports to the United States acting as the primary drag. The fourth quarter proved particularly disappointing: output contracted 0.6% on an annualized basis, missing both the Bank of Canada's projection for a flat reading and the consensus call for…
Read source

Trump invites countries affected by Hormuz closure to do it themselves; he won’t be there

Trump on Truth Social:

All of those countries that can’t get jet fuel because of the Strait of Hormuz, like the United Kingdom, which refused to get involved in the decapitation of Iran, I have a suggestion for you: Number 1, buy from the U.S., we have plenty, and Number 2, build up some delayed courage, go to the Strait, and just TAKE IT. You’ll have to start learning how to fight for yourself, the U.S.A. won’t be there to help you anymore, just like you weren’t there for us. Iran has been, essentially, decimated. The hard part is done. Go get your own oil! President DJT

Trump is basically confirming the WSJ report released in the APAC session saying that he would be open to end the war with Iran without the Strait of Hormuz opening…

Read source

Eurozone headline inflation picks up in March as energy prices surge on Middle East war

The preliminary CPI report for March sees headline annual inflation come in at 2.5%, just a touch softer than the 2.6% estimate. Still, it represents a notable bump to the 1.9% reading in February last month. The main cause for the jump is higher energy prices, as a result of the US-Iran conflict. Of note, energy prices were seen 4.9% higher than it was a year ago.

Other than that, food prices were seen up 2.4% compared to the same month one year ago. Meanwhile, services inflation was seen at 3.2% so that continues to remain a key sticking point for the ECB.

When looking at core prices though, the report was less worrying - at least for now. Core annual inflation was seen at 2.3%, missing slightly on estimates of 2.4%. That is also down a…

Read source

Tuesday 31st March 2026: Asia-Pacific Markets Volatile as Oil Prices Fall on Signs of U.S. De-Escalation With Iran


Global Markets:
  •  Asian Stock Markets : Nikkei down 1.14%, Shanghai Composite down 0.3% Hang Seng down 0.52% ASX up 0.63%
  • Commodities : Gold at $4,584.51 (0.20%) Silver at $72.145 (2.50%), Brent Oil at $107.71 (0.26%), WTI Oil at $103.57 (0.92%)
  • Rates : US 10-year yield at 4.324, UK 10-year yield at 4.9340, Germany 10-year yield at 3.039
News & Data:
  • (GBP) M4 Money Supply m/m  0.6%  to 0.1%  expected
Markets Update:  

Asia-Pacific markets swung sharply on Tuesday as oil prices reversed earlier gains after reports suggested President Donald Trump was seeking to avoid a prolonged Middle East conflict. Investors reacted quickly to signals that Washington may scale back military objectives, easing immediate supply…

Read source

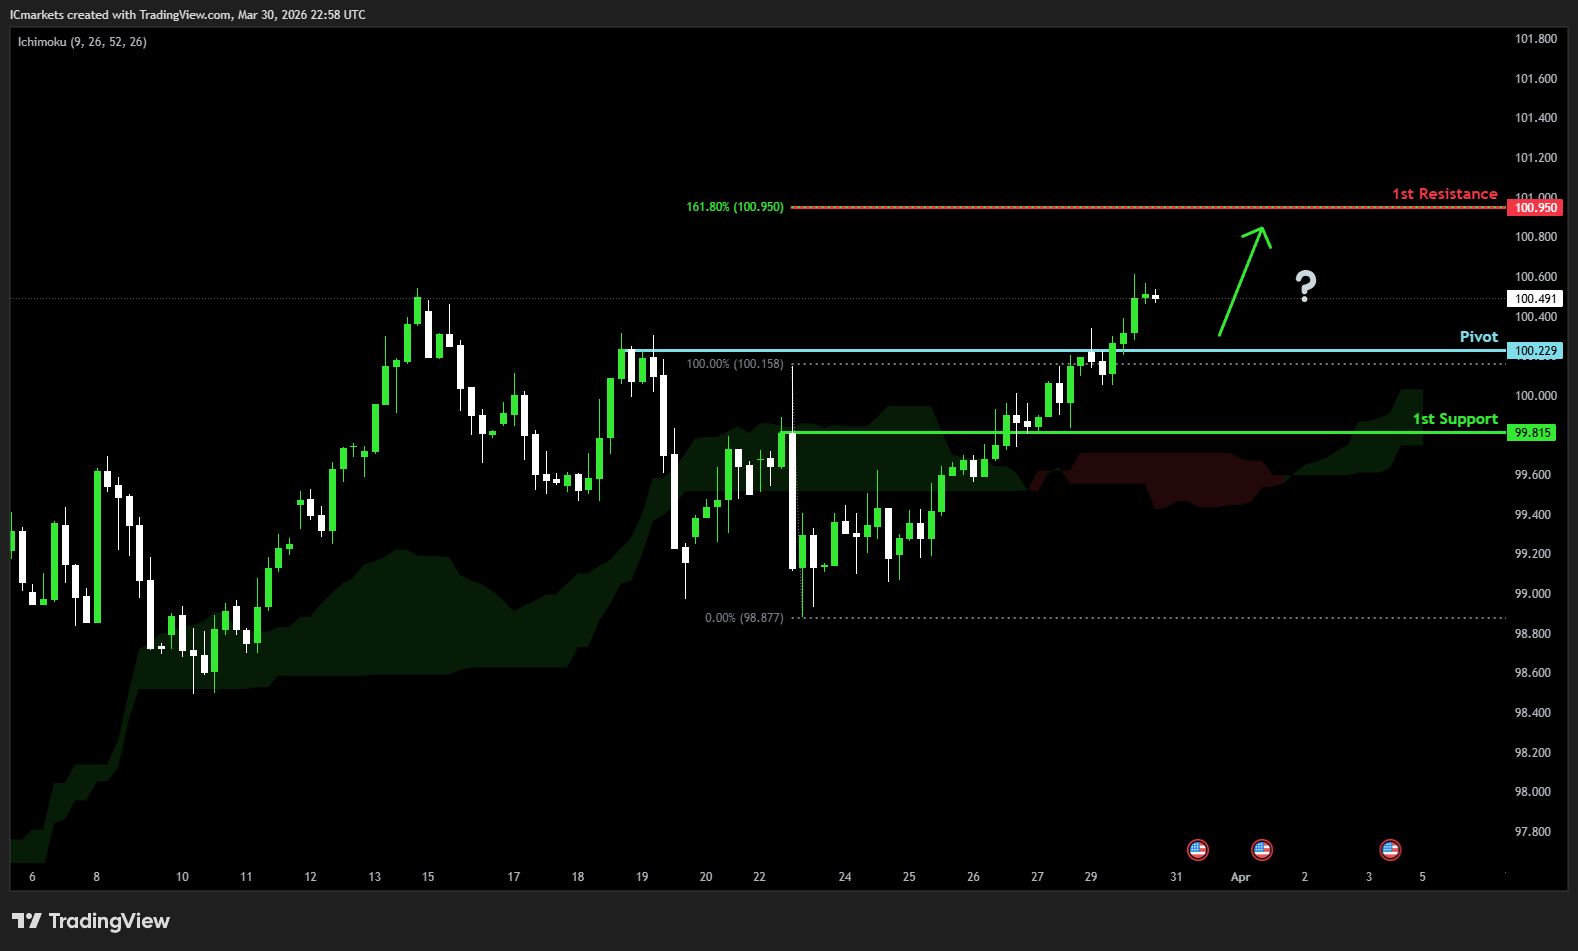
Tuesday 31st March 2026: Technical Outlook and Review

  DXY (U.S. Dollar Index):

Potential Direction: Bullish

Overall momentum of the chart: Bearish

The price could see a short-term pullback toward the pivot before rising again toward the 1st resistance.

Pivot: 100.22

Supporting reasons: Identified as a pullback support, where renewed buying pressure could emerge to push the price higher.

1st support: 99.81

Supporting reasons: Identified as an overlap support, indicating a potential area where the price could again stabilize.

1st resistance: 100.95
Supporting reasons: Identified as a resistance that aligns with the 161.8% Fibonacci extension, indicating a potential area that could halt any further upward movement

EUR/USD:

Potential Direction:…

Read source

Three Chinese ships confirmed to have passed through Strait of Hormuz

The ministry confirms that three Chinese ships have recently sailed through the Strait of Hormuz, adding that "we would like to express our gratitude for the assistance provided by all parties concerned". They didn't go so far to name which ships they are referring to but recent reports suggest that it is likely they are vessels tied to China's state-run COSCO Shipping.

For some context, these same ships were turned back on Friday last week as Iran continues to keep a firm stranglehold of control over the Strait of Hormuz. Two ships are said to be owned by COSCO Shipping with the other believed to be Hong Kong-owned Lotus Rising. Those were the three ships turned back at the end of last week and are believed to be allowed passage this time…

Read source

Germany March unemployment change 0k vs 2k expected

  • Prior 1k
  • Unemployment rate 6.3% vs 6.3% expected
  • Prior 6.3%

German unemployment remains unchanged in March with the jobless rate keeping steady on the month as well. The jobless figure overall remains the same as it was in February at 2.977 million. Well, this at least reaffirms the labour market has been holding up in recent months after having softened modestly in the first half of last year especially.

The labour office notes that: "As usual, the spring upturn in the labour market begins in March, however, without any significant momentum this year."

This article was written by Justin Low at investinglive.com.
Read source

IC Markets – Asia Fundamental Forecast | 31 March 2026

IC Markets – Asia Fundamental Forecast | 31 March 2026

What happened in the U.S. session?

The U.S. session overnight saw no fresh macro data but intense focus on the escalating U.S.-Iran war, pushing oil past $115/barrel amid Strait of Hormuz disruptions and reigniting inflation via prior 1.3% import price surges, driving Treasury yields to 4.44%+ and equities deeper into corrections (Nasdaq/Dow down >10% from peaks); crude oil, stocks, and bonds bore the brunt, while gold stabilized post-plunge and USD gained on Fed hawkishness.

What does it mean for the Asia Session?

Escalating Iran‑Gulf tensions, which are underpinning oil volatility and safe‑haven demand, while keeping a close eye on USD/JPY near intervention‑watch levels and the…

Read source

IC Markets – Europe Fundamental Forecast | 31 March 2026

IC Markets – Europe Fundamental Forecast | 31 March 2026

What happened in the Asia session?

Risk-off backdrop tied to the broader Middle‑East conflict and elevated oil prices, overlaid with softer‑than‑expected Tokyo CPI (which capped the yen rally) and mildly constructive but still vulnerable Chinese PMI prints, leading to a clear underperformance in JPY‑crosses such as USD/JPY near intervention‑watch levels, pressure on commodity‑linked AUD, and downside bias in regional equities, especially Japan and Korea, while oil and energy‑linked instruments remained well bid.

What does it mean for the Europe & US sessions?

Persistent growth fears and elevated oil prices are anchoring global risk‑off positioning, with the S&P 500 and Nasdaq near…

Read source

France March preliminary CPI +1.7% vs +1.6% y/y expected

  • Prior +0.9%
  • HICP +1.9% vs +1.9% y/y expected
  • Prior +1.1%

The headline estimate is the highest since August 2024 as French inflation picks up amid higher energy prices as a result of the US-Iran conflict. The monthly reading shows that consumer prices were up 0.9%, the steepest jump since February 2024.

The breakdown shows that food price inflation was seen at 1.8% (previously 2.0%) and services inflation at 1.7% (previously 1.6%). As such, core prices should keep thereabouts as in February with the latest spike here being largely energy-related. Of note, energy prices surged by 7.3% in March after exhibiting a 2.9% monthly decline in February.

But over time if allowed to become more entrenched, higher energy prices will spill over to other…

Read source

Germany February retail sales -0.6% vs +0.2% m/m expected

  • Prior -0.9%; revised to -1.1%

And once again, German retail sales underwhelms on expectations and this time it is being made to look worse than previous times. For one, it comes alongside a negative revision to the January figure. But more importantly, it paints a negative backdrop in the month before we even see the US-Iran conflict impact hit on prices, inflation, and the economy.

Food store sales declined by 1.4% on the month while non-food store retailing saw a 0.7% increase in sales. The latter at least helps to offset slightly the negative drag on the overall report.

This kind of backdrop is not quite what you'd like to see as price pressures have already been keeping more stubborn in Europe's largest economy. Now when you have to…

Read source