Ex-Dividend 1/04/2026
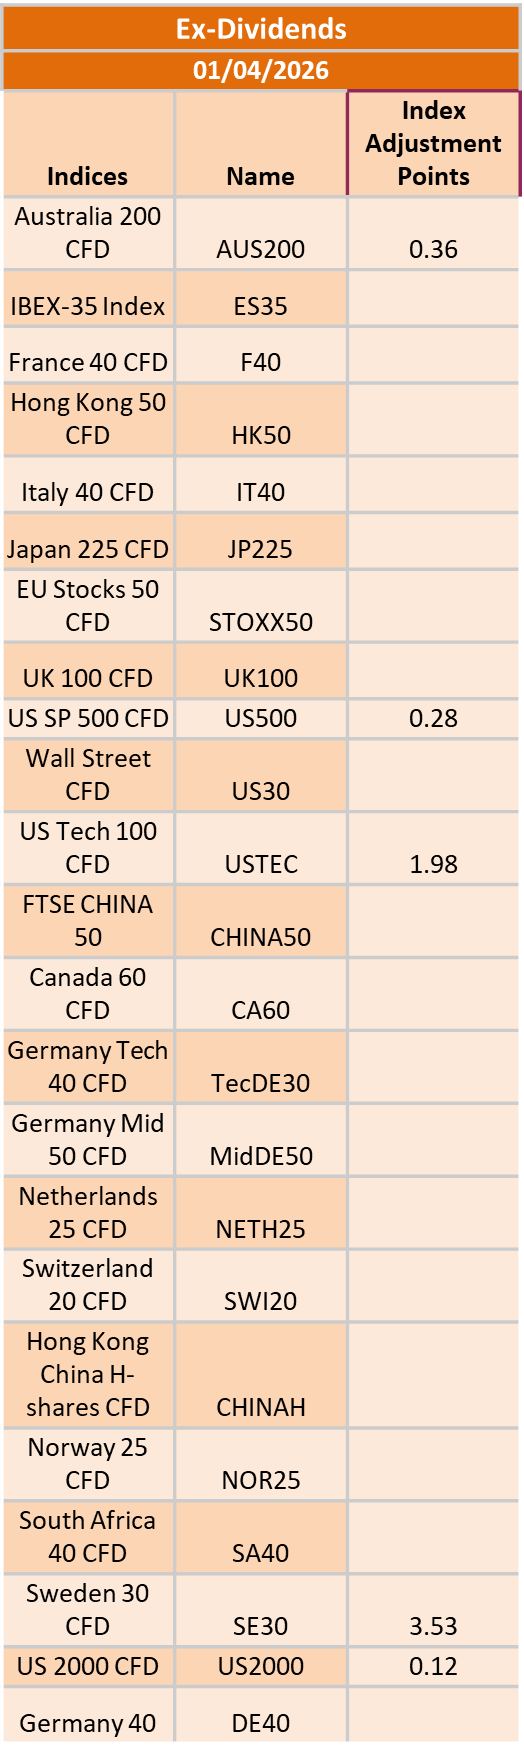
The post Ex-Dividend 1/04/2026 first appeared on IC Your Trading Edge | Official Blog.

Forex Market News .. collected from serval sources, all in one place for you to review.
[most entries here, will be auto-removed after 90 days]
The post Ex-Dividend 1/04/2026 first appeared on IC Your Trading Edge | Official Blog.
Trump's latest on Truth Social:
Iran’s New Regime President, much less Radicalized and far more intelligent than his predecessors, has just asked the United States of America for a CEASEFIRE! We will consider when Hormuz Strait is open, free, and clear. Until then, we are blasting Iran into oblivion or, as they say, back to the Stone Ages!!! President DJTTo be clear, Masoud Pezeshkian was the President before the conflict and remains the President.
The kink here is that it's not clear that he's in charge or was ever in charge. The President in Iran is oftentimes a ceremonial figure who runs the civilian side of the government and needs permission from the Supreme Leader and the IRGC for policy. Lately, there are increasing signs of a…
Details:
It's worth noting that the official Census Bureau advance estimate for February 2026 was originally scheduled for March 16 but has been delayed to April 1, 2026—so the government figures may be releasing today. The data below draws on the January Census report and the NRF's February reading based on alternative transaction data.
U.S. retail sales are published monthly by the Census Bureau as part of its Advance Monthly Retail Trade Survey, covering sales at stores, restaurants, and online…
Headlines:
Markets:
Details:
This is back-to-back decent readings after a long sting of poor numbers. Adding 62,000 jobs isn't exactly setting the world on fire but it takes the pressure of the employment side of the Fed's mandate and nudges them closer to holding rates or hiking them.
It's also nice to see growth in small businesses.
The negative bent to the report is that 58,000 of the 62,000 jobs were in education/health services. Construction also added 30K jobs while trade/transport/utilities lost 58K jobs and manufacturing fell 11K.
The US-Iran conflict continues to keep markets on edge but the coming day will be all about what US president Trump has to say. He is scheduled to deliver an address to the nation at 0100 GMT, with "important updates" on Iran. And he already gave a bit of a teaser yesterday in saying that:
"I had one goal. They will have no nuclear weapon, and that goal has been attained. They will not have nuclear weapons. But we’re finishing the job, and I think within maybe two weeks, maybe a couple of days longer, to do the job."
In essence, his address later looks to be one to hang the "mission accomplished" banner while trying to reaffirm to markets and the public that they will still need a few weeks to "clean up" what is left of the task.
Thus far,…
Spain's manufacturing sector activity falls back into contraction territory as the Middle East conflict starts to have an impact. The heightened uncertainty raised by the conflict and higher energy prices are feeding into supply-chain disruptions as well as rapidly rising prices for fuel and inputs. And that is resulting in manufacturers reporting accelerated declines in output and new orders.
Besides that, employment conditions also declined with the outlook also taking a hit amid a steep deterioration in manufacturing sector confidence.
Of note, input price inflation accelerated sharply to its highest level since late 2022. Expect this trend to also show up across the whole region with regards to the PMI readings today. In turn,…
Swiss manufacturing activity was surprisingly more robust in March, despite the impact of the Middle East conflict already starting to show up. Of note, production levels returned to expansion territory with it rising by 3.6 points to 50.6 in March. Meanwhile, the manufacturing orderbook also rose strongly by 7.3 points to 54.2 on the month.
That being said, there are some downsides that are worth noting. Purchasing prices saw a massive surge amid higher input cost inflation, with it climbing 15.5 points to 71.3. Meanwhile, suppliers' delivery times also increased significantly by 10.2 points to 63.6 on the month.
Those might well come and bite at Swiss manufacturing in the months ahead, should we see the Middle East conflict…
Key findings:
Comment:
Eleanor Dennison, Economist at S&P Global Market Intelligence, said:
“The impact of war in the Middle East is being felt by manufacturers in Italy, particularly in their supply chains as lead times on inputs lengthened to the most notable degree seen October 2022 amid reports of shortages and logistical challenges.
"Prices data showed a steep intensification of cost pressures, as firms widely reported paying more for raw materials, transportation and energy. The rate of cost inflation shot up to its highest level in…
Key findings:
Comment:
Rob Dobson, Director at S&P Global Market Intelligence:
“UK manufacturing output contracted for the first time in six months in March, as the war in the Middle East and ongoing concerns about domestic economic policy led to a scaling back of production.
"The impact of the war also caused noticeable shifts in the cost and supply chain backdrops. Delivery times lengthened to the greatest extent since mid-2022, while the acceleration in input price inflation was the steepest since the aftermath…
It's just a minor downgrade to the final estimate as France's manufacturing sector continues to stagnate in light of the Middle East conflict. The two biggest things to note are that suppliers' delivery times and input cost inflation both surged significantly on the month.
The former lengthened to its greatest degree since January 2023 while the latter saw a steep increase to its highest since December 2022.
Besides that, demand conditions also waned further with international customer demand seeing its steepest deterioration since July last year. That alongside an already weak domestic market sentiment.
HCOB notes that:
"The March PMI revealed an immediate impact from the war in the Middle East. The survey data, collected between…
Key findings:
Comment:
Phil Smith, Economics Associate Director at S&P Global Market Intelligence:
"The immediate impacts of the war in the Middle East on the German manufacturing sector are clear to see in March's PMI results. Most notably, input cost inflation has spiked higher on the back of the surge in oil and gas prices, registering its largest single-month rise on record.
"We're already starting to see signs of stress across supply chains, with lead times on inputs lengthening to the greatest extent since mid-2022. This has helped…